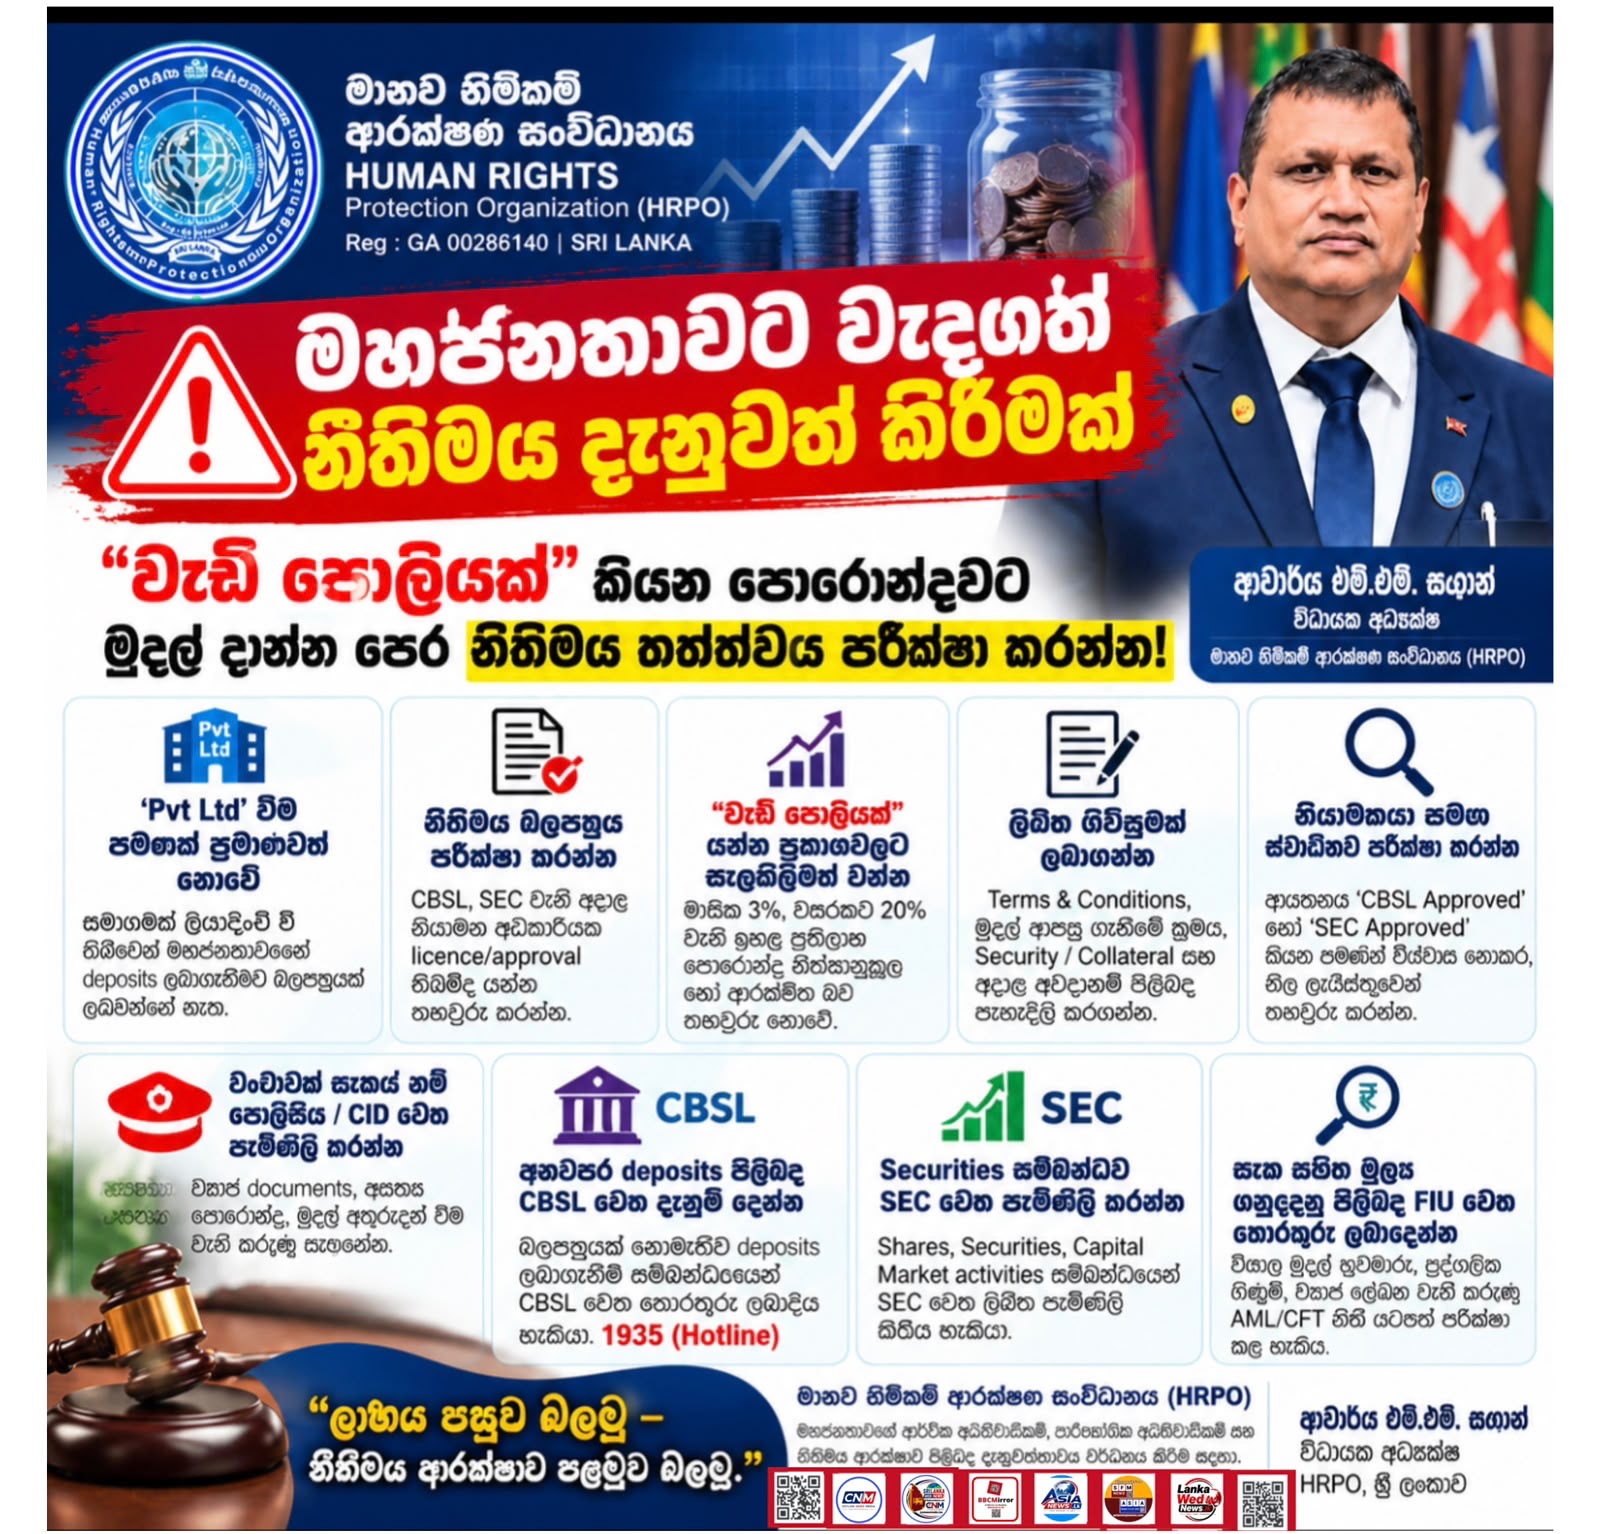
මහජනතාවට වැදගත් නීතිමය දැනුවත් කිරීමක්
https://chat.whatsapp.com/Knsroge4upyJzBjJLvNMQS?s=cl&p=i&mlu=4&ilr=4
වැඩි පොලියක්” හෝ “ඉහළ ප්රතිලාභයක්” යන පොරොන්දුවට මුදල් ලබාදීමට පෙර නීතිමය තත්ත්වය පරීක්ෂා කරන්න
මානව හිමිකම් ආරක්ෂණ සංවිධානය (HRPO)
විධායක අධ්යක්ෂ – ආචාර්ය එම්.එම්.සෆාන්
🔴 සමාගමක් “Pvt Ltd” ලෙස ලියාපදිංචි වී තිබීම පමණක් ප්රමාණවත් නොවේ
වර්තමානයේ ඇතැම් ආයතන, සමාගම් සහ පුද්ගලයන් විසින් “වැඩි පොලියක්”, “ස්ථිර ලාභයක්”, “මාසික ආදායමක්”, “Guaranteed Return”, “Risk-Free Investment” වැනි පොරොන්දු ලබාදෙමින් මහජනතාවගෙන් මුදල් ලබාගැනීමට උත්සාහ කරන අවස්ථා දක්නට ලැබේ.
මෙවැනි අවස්ථාවක සමාගමක් Registrar of Companies යටතේ ලියාපදිංචි වී තිබීම පමණක් එම ආයතනයට මහජනතාවගෙන් deposits ලබාගැනීමට හෝ finance business පවත්වාගෙන යාමට බලපත්රයක් ලබාදෙන්නේ නැත.
Company Registration ≠ Deposit-taking Licence
එබැවින් මුදල් ලබාදීමට පෙර එම ආයතනය කුමන නීතියක් යටතේ සහ කුමන නියාමන අධිකාරියක් යටතේ ක්රියාත්මක වන්නේද යන්න පරීක්ෂා කළ යුතුය.
1. Finance Business Act No. 42 of 2011
Finance Business Act No. 42 of 2011 යටතේ අදාළ බලපත්රයක් නොමැතිව finance business පවත්වාගෙන යාම හෝ මහජනතාවගෙන් deposits ලබාගැනීම සම්බන්ධයෙන් නීතිමය සීමා පවතී.
එම පනතේ Section 48 යටතේ, බලයලත් හෝ නීතියෙන් නිදහස් කර ඇති පාර්ශ්වයක් නොවන පුද්ගලයෙකු හෝ ආයතනයක් විසින් මහජනතාවගෙන් deposits ලබාගැනීමට සෘජුව හෝ වක්රව දැන්වීම් මගින් ඉල්ලා සිටීම සම්බන්ධයෙන් තහනමක් පවතී.
ඒ නිසා Facebook, WhatsApp, TikTok, YouTube, වෙබ් අඩවි, පුවත්පත් හෝ වෙනත් මාධ්ය හරහා මුදල් ඉල්ලා සිටින ආයතන පිළිබඳව විශේෂ අවධානයක් යොමු කළ යුතුය.
2. CBSL බලපත්රය පරීක්ෂා කරන්න
ශ්රී ලංකා මහ බැංකුව (CBSL) අනුව සාමාන්යයෙන් මහජනතාවගෙන් deposits ලබාගැනීමට බලය ඇති ප්රධාන ආයතන කාණ්ඩ අතර:
* Licensed Commercial Banks
* Licensed Specialised Banks
* Licensed Finance Companies
ඇතුළත් වේ. නීතියෙන් විශේෂයෙන් නිදහස් කර ඇති ඇතැම් ආයතනද පවතී.
එබැවින් ආයතනයක්:
“CBSL Approved”
“CBSL Registered”
“CBSL Regulated”
යනුවෙන් සඳහන් කළ පමණින් එය විශ්වාස නොකරන්න.
ආයතනයේ නම සහ licence තත්ත්වය CBSL නිල ලැයිස්තුවෙන් ස්වාධීනව පරීක්ෂා කරන්න.
3. “Deposit” ද? “Investment” ද?
ආයතනයක් “Investment” යන වචනය භාවිත කළ පමණින් එම ගනුදෙනුව නීතිය යටතේ deposit-taking activity එකක් නොවන බව තීරණය කළ නොහැක.
උදාහරණයක් ලෙස:
“රු. 1,000,000ක් ලබාදෙන්න. සෑම මාසයකම 3%ක ප්රතිලාභයක් ලබාදෙන්නම්.”
වැනි යෝජනාවක් ඉදිරිපත් කරන්නේ නම්, එම ගනුදෙනුවේ සැබෑ නීතිමය ස්වභාවය හඳුනාගත යුතුය.
මුදල් ලබාදීමට පෙර මෙය:
* Deposit එකක්ද?
* Investment එකක්ද?
* Loan එකක්ද?
* Shares/Securities මිලදී ගැනීමක්ද?
* Collective Investment Scheme එකක්ද?
යන්න පැහැදිලි කරගන්න.
ගිවිසුමේ නමට වඩා ගනුදෙනුවේ සැබෑ ස්වභාවය වැදගත් වේ.
4. මුදල් ලබාදීමට පෙර මෙම කරුණු පරීක්ෂා කරන්න
ආයතනය පිළිබඳව අවම වශයෙන් පහත කරුණු පරීක්ෂා කරන්න:
1. Company Registration
2. Company Registration Number
3. Directors සහ අදාළ හිමිකාරීත්ව තොරතුරු
4. ආයතනයේ සැබෑ ව්යාපාරික කටයුත්ත
5. අදාළ නියාමන අධිකාරිය
6. Licence / Approval Number
7. Licence එකේ වලංගුභාවය
8. එම licence එකෙන් අවසර දී ඇති ක්රියාකාරකම්
9. Deposit-taking authority තිබේද?
10. Investment/Securities approval අවශ්යද?
11. Written Agreement
12. Terms & Conditions
13. Audited Financial Statements
14. Security / Collateral තිබේද?
15. මුදල් යවන්නේ කුමන බැංකු ගිණුමකටද?
16. මුදල් ආපසු ලබාගැනීමේ නීතිමය ක්රමය කුමක්ද?
5. “වැඩි පොලියක්” සහ “ස්ථිර ලාභයක්” පිළිබඳව සැලකිලිමත් වන්න
“මාසිකව 3%”, “වසරකට 20%”, “Guaranteed Profit”, “Risk-Free” වැනි ප්රකාශයක් තිබීමෙන් පමණක් එම ආයෝජනය නීත්යානුකූල හෝ ආරක්ෂිත බව තහවුරු නොවේ.
ප්රතිලාභය වැඩි වන තරමට අවදානම පිළිබඳවද පැහැදිලි තොරතුරු ලබාගන්න.
විශේෂයෙන්:
“පාඩුවක් සිදුවුවහොත් වගකීම දරන්නේ කවුද?”
“මුදල් ආපසු නොගෙවුවහොත් අපට ඇති නීතිමය අයිතිය කුමක්ද?”
යන ප්රශ්න අසන්න.
6. SEC නීති පිළිබඳව අවධානය යොමු කරන්න
මුදල් ලබාගැනීම shares, securities, debentures, public offers, capital-market activities හෝ වෙනත් SEC නියාමනයට යටත් ක්රියාකාරකමකට සම්බන්ධ නම්, Securities and Exchange Commission of Sri Lanka (SEC) යටතේ අදාළ නියාමන අවශ්යතා පරීක්ෂා කළ යුතුය.
ආයතනය “SEC Approved” යනුවෙන් පවසන්නේ නම්:
“SEC approval / licence reference number එක කුමක්ද?”
යනුවෙන් ලිඛිතව විමසා, එය SEC සමඟ ස්වාධීනව තහවුරු කරගන්න.
7. සැක සහිත මූල්ය ගනුදෙනු පිළිබඳව අවධානය
ගනුදෙනුවකදී:
* විශාල මුදල් ප්රමාණ;
* මුදල් මූලාශ්රය පැහැදිලි නොවීම;
* වෙනත් පුද්ගලයන්ගේ bank accounts;
* අසාමාන්ය cash transactions;
* third-party transfers;
* සැක සහිත විදේශීය මුදල් හුවමාරු;
* ව්යාජ ලේඛන;
වැනි කරුණු තිබේ නම්, එය Anti-Money Laundering / Countering the Financing of Terrorism (AML/CFT) සම්බන්ධ නීතිමය පරීක්ෂණයකටද අදාළ විය හැකිය.
ශ්රී ලංකාවේ මේ සම්බන්ධ ප්රධාන නීති අතර:
* Prevention of Money Laundering Act No. 5 of 2006
* Financial Transactions Reporting Act No. 6 of 2006
* Convention on the Suppression of Terrorist Financing Act No. 25 of 2005
8. වංචාවක් පිළිබඳ සැකයක් ඇතිවුවහොත්
යම් ආයතනයක්:
* ව්යාජ licence පෙන්වන්නේ නම්;
* ව්යාජ CBSL/SEC approval ප්රකාශ කරන්නේ නම්;
* ව්යාජ ලේඛන භාවිත කරන්නේ නම්;
* අසත්ය ප්රතිලාභ පොරොන්දු ලබාදෙන්නේ නම්;
* මුදල් ලබාගෙන පසුව සම්බන්ධ වීම නවත්වන්නේ නම්;
* මුදල් ආපසු ලබාදීම ප්රතික්ෂේප කරන්නේ නම්;
* පුද්ගලික bank accounts වෙත මුදල් යැවීමට බල කරන්නේ නම්;
* තවත් පුද්ගලයන් ගෙන්වා ගැනීම සඳහා commission ලබාදෙන්නේ නම්;
එම කරුණු අනුව පොලිසිය/CID, CBSL, SEC හෝ වෙනත් අදාළ නියාමන ආයතනයකට පැමිණිලි කිරීම සලකා බැලිය යුතුය.
9. පොලිසිය / CID වෙත පැමිණිලි කිරීම
වංචාව, ව්යාජ ලේඛන, ව්යාජ බලපත්ර, මුදල් වංචා හෝ online financial fraud පිළිබඳ සාධාරණ සැකයක් තිබේ නම් ශ්රී ලංකා පොලිසිය වෙත පැමිණිලි කළ හැකිය.
පැමිණිල්ලක් කරන විට සිද්ධිය දිනය, මුදල, පුද්ගලයා/ආයතනය, bank account, දුරකථන අංක, ගිවිසුම් සහ අනෙකුත් සාක්ෂි සමඟ පැහැදිලිව ඉදිරිපත් කරන්න.
Online complaint පහසුකම් භාවිත කරන්නේ නම්, පැමිණිල්ලේ reference number එක ආරක්ෂිතව තබාගන්න.
10. CBSL වෙත පැමිණිලි කිරීම
පහත කරුණු සම්බන්ධයෙන් CBSL වෙත තොරතුරු/පැමිණිලි ඉදිරිපත් කිරීම සලකා බැලිය හැකිය:
* බලපත්රයක් නොමැතිව deposits ලබාගැනීම;
* අනවසර finance business;
* “CBSL Approved” යනුවෙන් අසත්ය ප්රකාශ කිරීම;
* අදාළ licence එක තහවුරු කළ නොහැකි වීම;
* අනවසර deposit-taking scheme.
CBSL විසින් අනවසර මූල්ය ක්රියාකාරකම් සම්බන්ධයෙන් නීතිමය ක්රියාමාර්ග ගෙන ඇති අතර, 2026 දී freezing orders සම්බන්ධ නිල නිවේදනද නිකුත් කර ඇත.
CBSL Hotline – 1935
11. SEC වෙත පැමිණිලි කිරීම
ගනුදෙනුව securities හෝ capital-market activity එකකට අදාළ නම් SEC වෙත පැමිණිලි කළ හැකිය.
විශේෂයෙන්:
* Shares
* Securities
* Public Offers
* Unit Trusts
* Stockbrokers
* Stock Dealers
* Capital-market intermediaries
වැනි ක්රියාකාරකම් සම්බන්ධයෙන් අදාළ නියාමන තත්ත්වය පරීක්ෂා කරන්න.
12. පැමිණිල්ලක් කිරීමට පෙර සාක්ෂි ආරක්ෂා කරගන්න
පහත ලේඛන හා සාක්ෂි මකා නොදමා ආරක්ෂිතව තබාගන්න:
මුදල් ගෙවීම්
* Bank slips
* Bank statements
* Online transfer confirmations
* Receipts
ගිවිසුම්
* Investment Agreement
* Deposit Agreement
* Loan Agreement
* Terms & Conditions
ප්රචාරණ
* Facebook posts
* WhatsApp messages
* Website screenshots
* TikTok/YouTube links
* Posters
* Brochures
සන්නිවේදන
* Emails
* SMS
* WhatsApp chats
* දුරකථන අංක
* නීතියට අනුකූලව ලබාගත් අනෙකුත් සාක්ෂි
සාක්ෂි මකා දැමීම හෝ වෙනස් කිරීමෙන් වළකින්න.
13. “මුදල් ආපසු දෙන්න තවත් මුදල් ගෙවන්න” කියන්නේ නම්
මුදල් ආපසු ලබාදීමට:
“Tax එකක් ගෙවන්න.”
“Release Fee එකක් ගෙවන්න.”
“Processing Fee එකක් ගෙවන්න.”
“Account Unlock Fee එකක් ගෙවන්න.”
“CBSL Clearance Fee එකක් ගෙවන්න.”
වැනි හේතු දක්වමින් තවත් මුදල් ඉල්ලා සිටින්නේ නම්, අදාළ නිල ආයතනය සමඟ ස්වාධීනව තහවුරු කරගැනීමකින් තොරව තවත් මුදල් නොගෙවන්න.
14. SLDIS ආරක්ෂාව පිළිබඳ වැදගත් කරුණක්
බලයලත් ආයතනයක සුදුසුකම් ලත් deposit එකක් සහ සාමාන්ය “investment” එකක් එකම දෙයක් නොවේ.
CBSL සඳහන් කරන පරිදි, Sri Lanka Deposit Insurance Scheme (SLDIS) යටතේ සුදුසුකම් ලත් deposits සඳහා එක් තැන්පත්කරුවෙකුට එක් ආයතනයක් සම්බන්ධයෙන් අදාළ උපරිම වන්දි සීමාවක් පවතී.
එය සියලුම ආයෝජන, shares, securities හෝ පුද්ගලික investment schemes සඳහා සහතිකයක් නොවේ.
එබැවින් “SLDIS තියෙනවා” යන ප්රකාශය පමණක් මත කිසිදු ආයෝජන තීරණයක් නොගන්න.
15. HRPO හි අවසන් මහජන පණිවිඩය
“ලාභය පසුව බලමු – නීතිමය ආරක්ෂාව පළමුව බලමු.”
ඔබේ ජීවිත කාලයේ ඉතිරිකිරීම්, විශ්රාමික මුදල්, දරුවන්ගේ අධ්යාපන මුදල් හෝ ව්යාපාරික මුදල් කිසියම් ආයතනයකට ලබාදීමට පෙර:
නියාමකයා හඳුනාගන්න.
Licence එක පරීක්ෂා කරන්න.
ගිවිසුම කියවන්න.
අවදානම තේරුම් ගන්න.
සාක්ෂි ආරක්ෂා කරගන්න.
සැකයක් ඇත්නම් මුදල් ලබා නොදෙන්න.
මතක තබාගන්න:
“Pvt Ltd” සමාගමක් වීම පමණක් මහජනතාවගෙන් deposits ලබාගැනීමට බලපත්රයක් නොවේ.
“CBSL Approved” යන ප්රකාශය නිල මූලාශ්රයකින් තහවුරු කරන්න.
“Guaranteed Profit” යන පොරොන්දුව පමණක් මත මුදල් ලබා නොදෙන්න.
ඔබේ මුදල් – ඔබේ වගකීම – ඔබේ නීතිමය අයිතිය.
මානව හිමිකම් ආරක්ෂණ සංවිධානය (HRPO)
මහජනතාවගේ ආර්ථික අයිතිවාසිකම්, පාරිභෝගික අයිතිවාසිකම් සහ නීතිමය ආරක්ෂාව පිළිබඳ දැනුවත්භාවය වර්ධනය කිරීම සඳහා මෙම මහජන දැනුවත් කිරීම ඉදිරිපත් කරනු ලැබේ.
ආචාර්ය එම්.එම්.සෆාන්
විධායක අධ්යක්ෂ
මානව හිමිකම් ආරක්ෂණ සංවිධානය (HRPO), ශ්රී ලංකාව
Important Legal Awareness Notice to the Public
Before Investing Your Money Based on Promises of “High Interest” or “High Returns”, Check the Legal Status
Human Rights Protection Organization (HRPO)
Executive Director – Dr. M. M. Shafaan
Today, various institutions, companies and individuals may approach the public with promises such as “high interest,” “guaranteed profits,” “monthly income,” “guaranteed returns,” or “risk-free investments.”
Before handing over your hard-earned money to any institution, always verify its legal status, licence, regulatory authority and the legal basis of the transaction.
Being registered as a “Pvt Ltd” company is not enough
Registration with the Registrar of Companies does not by itself give a company the authority to accept deposits from the public or conduct a finance business.
Company Registration ≠ Deposit-Taking Licence
Therefore, before investing, verify under which law the institution operates and which regulatory authority supervises its activities.
1. Finance Business Act No. 42 of 2011
The Finance Business Act No. 42 of 2011 places legal restrictions on conducting finance business or accepting deposits without the required authority.
Section 48 also contains restrictions relating to directly or indirectly inviting the public to make deposits through advertisements where the relevant legal authority is absent.
Therefore, be particularly cautious about advertisements on Facebook, WhatsApp, TikTok, YouTube, websites, newspapers and other media that seek money from the public.
2. Check the CBSL Licence
According to the Central Bank of Sri Lanka (CBSL), the main categories of institutions generally authorised to accept deposits from the public include:
* Licensed Commercial Banks
* Licensed Specialised Banks
* Licensed Finance Companies
There are also certain institutions specifically exempted by law.
Therefore, do not rely solely on claims such as:
“CBSL Approved”
“CBSL Registered”
“CBSL Regulated”
Independently verify the institution and its licence through the official CBSL sources.
3. Is it a “Deposit” or an “Investment”?
Simply calling a transaction an “Investment” does not necessarily determine its legal nature.
For example:
“Give us Rs. 1,000,000 and we will pay you a 3% return every month.”
Before providing money, clarify whether the transaction is:
* A Deposit
* An Investment
* A Loan
* Purchase of Shares/Securities
* A Collective Investment Scheme
The actual nature of the transaction is more important than the title given to the agreement.
4. Check These Matters Before Giving Your Money
Check at least the following:
1. Company Registration
2. Company Registration Number
3. Directors and relevant ownership information
4. Actual business activity
5. Relevant regulatory authority
6. Licence / Approval Number
7. Validity of the licence
8. Activities permitted under the licence
9. Whether the institution is authorised to accept deposits
10. Whether investment/securities approval is required
11. Written Agreement
12. Terms & Conditions
13. Audited Financial Statements
14. Security / Collateral
15. Bank account to which the money will be transferred
16. Legal procedure for withdrawing or recovering your money
5. Be Careful About “High Interest” and “Guaranteed Profits”
Statements such as “3% per month,” “20% per year,” “Guaranteed Profit,” or “Risk-Free” do not, by themselves, prove that an investment is legal or safe.
Ask:
“Who is responsible if the investment suffers a loss?”
“What are my legal rights if my money is not returned?”
6. Pay Attention to SEC Regulations
If the transaction involves shares, securities, debentures, public offers, capital-market activities or other activities regulated by the Securities and Exchange Commission of Sri Lanka (SEC), verify the applicable regulatory requirements.
If an institution claims to be “SEC Approved,” ask for the relevant approval/licence reference number and independently verify it with the SEC.
7. Be Alert to Suspicious Financial Transactions
Large unexplained transactions, third-party bank accounts, unusual cash transactions, suspicious international transfers, unclear sources of funds or false documents may raise Anti-Money Laundering / Countering the Financing of Terrorism (AML/CFT) concerns.
Relevant legislation includes:
* Prevention of Money Laundering Act No. 5 of 2006
* Financial Transactions Reporting Act No. 6 of 2006
* Convention on the Suppression of Terrorist Financing Act No. 25 of 2005
8. If You Suspect Fraud
If an institution:
* Provides a false licence;
* Falsely claims CBSL/SEC approval;
* Uses false documents;
* Makes misleading promises of returns;
* Takes money and subsequently disappears;
* Refuses to return money;
* Forces customers to transfer money to personal bank accounts; or
* Offers commissions for recruiting additional people,
consider reporting the matter, depending on its nature, to the Sri Lanka Police/CID, CBSL, SEC or other relevant regulatory authorities.
9. Complaints to Police / CID
If there is reasonable suspicion of fraud, forged documents, false licences, financial fraud or online financial fraud, a complaint may be made to the Sri Lanka Police.
Include the relevant dates, amounts, names of persons/institutions, bank account details, telephone numbers, agreements and other evidence.
If you use an online complaint facility, keep the complaint reference number safely.
10. Complaints to CBSL
Consider providing information or making a complaint to CBSL regarding:
* Unauthorised deposit-taking;
* Unauthorised finance business;
* False claims of being “CBSL Approved”;
* An unverifiable licence; or
* An unauthorised deposit-taking scheme.
CBSL Hotline: 1935
11. Complaints to SEC
If the matter relates to securities or capital-market activities, consider making a complaint to the SEC.
This may include matters relating to:
* Shares
* Securities
* Public Offers
* Unit Trusts
* Stockbrokers
* Stock Dealers
* Capital-market intermediaries
12. Preserve Your Evidence
Do not delete or alter relevant evidence, including:
Payment Evidence
* Bank slips
* Bank statements
* Online transfer confirmations
* Receipts
Agreements
* Investment Agreements
* Deposit Agreements
* Loan Agreements
* Terms & Conditions
Advertising
* Facebook posts
* WhatsApp messages
* Website screenshots
* TikTok/YouTube links
* Posters
* Brochures
Communications
* Emails
* SMS
* WhatsApp chats
* Telephone numbers
* Other evidence lawfully obtained
13. If They Ask You to Pay More Money to Get Your Money Back
If someone says:
“Pay a tax.”
“Pay a release fee.”
“Pay a processing fee.”
“Pay an account-unlock fee.”
“Pay a CBSL clearance fee.”
do not make another payment without independently verifying the request with the relevant official authority.
14. Important Point About SLDIS
A qualifying deposit held with an authorised institution and an ordinary “investment” are not necessarily the same thing.
The Sri Lanka Deposit Insurance Scheme (SLDIS) applies to qualifying deposits subject to its applicable terms and limits.
It does not mean that all investments, shares, securities or private investment schemes are guaranteed.
Therefore, do not make an investment decision merely because someone claims that “SLDIS protection is available.”
HRPO’s Message to the Public
“Look at the legal protection first – profit comes later.”
Before giving your life savings, retirement funds, children’s education funds or business funds to any institution:
Identify the regulator.
Verify the licence.
Read the agreement.
Understand the risks.
Preserve your evidence.
If you have doubts, do not hand over your money.
Remember:
Being a “Pvt Ltd” company does not by itself mean that the company is authorised to accept deposits from the public.
Verify any claim of “CBSL Approved” through official sources.
Do not invest solely because of a promise of “Guaranteed Profit.”
Your Money – Your Responsibility – Your Legal Rights.
Human Rights Protection Organization (HRPO), Sri Lanka
This public awareness notice is issued to promote awareness of economic rights, consumer rights and legal protection.
Dr. M. M. Shafaan
Executive Director
Human Rights Protection Organization (HRPO), Sri Lanka
பொதுமக்களுக்கு முக்கியமான சட்ட விழிப்புணர்வு அறிவிப்பு
அதிக வட்டி” அல்லது “அதிக வருமானம்” என்ற வாக்குறுதியின் அடிப்படையில் பணத்தை முதலீடு செய்வதற்கு முன் சட்டபூர்வமான நிலையைச் சரிபார்க்கவும்
மனித உரிமைகள் பாதுகாப்பு அமைப்பு (HRPO)
நிறைவேற்றுப் பணிப்பாளர் – டாக்டர் M. M. Shafaan
தற்போது பல்வேறு நிறுவனங்கள், கம்பனிகள் மற்றும் தனிநபர்கள் “அதிக வட்டி”, “உத்தரவாதமான இலாபம்”, “மாதாந்த வருமானம்”, “உத்தரவாதமான வருமானம்” அல்லது “ஆபத்தற்ற முதலீடு” போன்ற வாக்குறுதிகளை வழங்கி பொதுமக்களிடமிருந்து பணத்தைப் பெற முயற்சிக்கும் சந்தர்ப்பங்கள் காணப்படுகின்றன.
எனவே, நீங்கள் கடினமாக உழைத்து சேமித்த பணத்தை எந்தவொரு நிறுவனத்திற்கும் வழங்குவதற்கு முன், அந்நிறுவனத்தின் சட்டபூர்வ நிலை, உரிமம், ஒழுங்குமுறை அதிகாரம் மற்றும் பணப் பரிவர்த்தனையின் சட்ட அடிப்படை ஆகியவற்றை கட்டாயமாகச் சரிபார்க்கவும்.
Pvt Ltd” நிறுவனமாகப் பதிவு செய்யப்பட்டிருப்பது மட்டும் போதுமானதல்ல
ஒரு நிறுவனம் Registrar of Companies கீழ் பதிவு செய்யப்பட்டிருப்பது மட்டுமே, அந்த நிறுவனத்திற்கு பொதுமக்களிடமிருந்து வைப்புகளை (Deposits) ஏற்றுக்கொள்ளவோ அல்லது நிதி வணிகத்தை (Finance Business) நடத்தவோ தானாகவே அதிகாரம் வழங்காது.
Company Registration ≠ Deposit-Taking Licence
எனவே, முதலீடு செய்வதற்கு முன் அந்த நிறுவனம் எந்த சட்டத்தின் கீழ் செயல்படுகிறது மற்றும் எந்த ஒழுங்குமுறை அதிகாரத்தால் கண்காணிக்கப்படுகிறது என்பதைச் சரிபார்க்க வேண்டும்.
1. Finance Business Act No. 42 of 2011
Finance Business Act No. 42 of 2011 இன் கீழ் தேவையான அதிகாரம் அல்லது உரிமம் இல்லாமல் நிதி வணிகத்தை நடத்துவதற்கும் பொதுமக்களிடமிருந்து வைப்புகளைப் பெறுவதற்கும் சட்டரீதியான கட்டுப்பாடுகள் உள்ளன.
அத்துடன், அந்தச் சட்டத்தின் Section 48 இன் கீழ், உரிய சட்ட அதிகாரம் இல்லாத நபர் அல்லது நிறுவனம் பொதுமக்களிடமிருந்து வைப்புகளைப் பெறுவதற்காக நேரடியாகவோ மறைமுகமாகவோ விளம்பரங்கள் மூலம் அழைப்பு விடுப்பதற்கும் கட்டுப்பாடுகள் உள்ளன.
எனவே, Facebook, WhatsApp, TikTok, YouTube, இணையத்தளங்கள், பத்திரிகைகள் மற்றும் பிற ஊடகங்கள் மூலம் பொதுமக்களிடமிருந்து பணம் கோரும் நிறுவனங்கள் தொடர்பாக மிகுந்த கவனம் செலுத்த வேண்டும்.
2. CBSL உரிமத்தைச் சரிபார்க்கவும்
இலங்கை மத்திய வங்கியின் (CBSL) தகவலின்படி, பொதுமக்களிடமிருந்து வைப்புகளைப் பெறுவதற்கு பொதுவாக அதிகாரம் பெற்ற நிறுவனங்களின் முக்கிய வகைகளில்:
* Licensed Commercial Banks
* Licensed Specialised Banks
* Licensed Finance Companies
ஆகியவை அடங்குகின்றன.
சட்டத்தால் குறிப்பாக விலக்கு அளிக்கப்பட்ட சில நிறுவனங்களும் இருக்கலாம்.
எனவே, ஒரு நிறுவனம்:
“CBSL Approved”
“CBSL Registered”
“CBSL Regulated”
என்று கூறுவதால் மட்டும் நம்ப வேண்டாம்.
அந்நிறுவனத்தின் பெயர் மற்றும் உரிம நிலையை CBSL-ன் அதிகாரப்பூர்வ தகவல் மூலம் சுயமாகச் சரிபார்க்கவும்.
3. இது “Deposit” ஆகுமா? “Investment” ஆகுமா?
ஒரு பரிவர்த்தனைக்கு “Investment” என்று பெயரிடப்பட்டிருப்பது மட்டும் அதன் சட்டபூர்வ தன்மையை தீர்மானிக்காது.
உதாரணமாக:
“ரூ. 1,000,000 வழங்குங்கள். ஒவ்வொரு மாதமும் 3% வருமானம் வழங்குகிறோம்.”
என்ற முன்மொழிவு வழங்கப்பட்டால், பணத்தை வழங்குவதற்கு முன் அந்தப் பரிவர்த்தனை:
* Deposit ஆகுமா?
* Investment ஆகுமா?
* Loan ஆகுமா?
* Shares/Securities கொள்வனவு ஆகுமா?
* Collective Investment Scheme ஆகுமா?
என்பதை தெளிவாக அறிந்து கொள்ளுங்கள்.
ஒப்பந்தத்திற்கு வழங்கப்பட்ட பெயரை விட, பரிவர்த்தனையின் உண்மையான தன்மையே முக்கியமானது.
4. பணத்தை வழங்குவதற்கு முன் இந்த விடயங்களைச் சரிபார்க்கவும்
குறைந்தபட்சம் பின்வரும் விடயங்களைச் சரிபார்க்கவும்:
1. நிறுவனப் பதிவு
2. Company Registration Number
3. Directors மற்றும் உரிமை தொடர்பான தகவல்கள்
4. நிறுவனத்தின் உண்மையான வணிக நடவடிக்கை
5. தொடர்புடைய ஒழுங்குமுறை அதிகாரம்
6. Licence / Approval Number
7. உரிமத்தின் செல்லுபடியாகும் காலம்
8. அந்த உரிமத்தின் கீழ் அனுமதிக்கப்பட்ட நடவடிக்கைகள்
9. பொதுமக்களிடமிருந்து வைப்புகளைப் பெறுவதற்கான அதிகாரம் உள்ளதா?
10. Investment/Securities approval தேவையா?
11. Written Agreement
12. Terms & Conditions
13. Audited Financial Statements
14. Security / Collateral
15. பணம் செலுத்த வேண்டிய வங்கிக் கணக்கு
16. பணத்தை மீளப் பெறுவதற்கான சட்ட நடைமுறை
5. “அதிக வட்டி” மற்றும் “உத்தரவாதமான இலாபம்” குறித்து எச்சரிக்கையாக இருங்கள்
“மாதத்திற்கு 3%”, “வருடத்திற்கு 20%”, “Guaranteed Profit”, “Risk-Free” போன்ற கூற்றுகள் இருப்பதால் மட்டும் அந்த முதலீடு சட்டபூர்வமானது அல்லது பாதுகாப்பானது என்று நிரூபிக்கப்படாது.
பின்வரும் கேள்விகளை கேளுங்கள்:
“முதலீட்டில் நஷ்டம் ஏற்பட்டால் அதற்கு யார் பொறுப்பு?”
மற்றும்
“எனது பணம் திருப்பிச் செலுத்தப்படாவிட்டால் எனக்குள்ள சட்ட உரிமைகள் என்ன?”
6. SEC விதிமுறைகள் தொடர்பாக கவனம் செலுத்தவும்
பரிவர்த்தனை Shares, Securities, Debentures, Public Offers, Capital-Market Activities அல்லது Securities and Exchange Commission of Sri Lanka (SEC) மூலம் ஒழுங்குபடுத்தப்படும் நடவடிக்கைகளுடன் தொடர்புடையதாக இருந்தால், அதற்கான ஒழுங்குமுறைத் தேவைகளைச் சரிபார்க்கவும்.
ஒரு நிறுவனம் “SEC Approved” என்று கூறினால்:
“SEC approval / licence reference number என்ன?”
என்று கேட்டு, அதனை SEC உடன் சுயமாகச் சரிபார்க்கவும்.
7.சந்தேகத்திற்கிடமான நிதிப் பரிவர்த்தனைகள் குறித்து எச்சரிக்கையாக இருங்கள்
பின்வரும் விடயங்கள் காணப்பட்டால்:
* விளக்கம் இல்லாத பெரிய தொகை பரிவர்த்தனைகள்;
* மூன்றாம் நபர்களின் வங்கிக் கணக்குகள்;
* வழக்கத்திற்கு மாறான பணப் பரிவர்த்தனைகள்;
* சந்தேகத்திற்கிடமான சர்வதேச பணப் பரிமாற்றங்கள்;
* பணத்தின் மூலாதாரம் தெளிவாக இல்லாமை;
* போலியான ஆவணங்கள்;
அவை Anti-Money Laundering / Countering the Financing of Terrorism (AML/CFT) தொடர்பான சட்ட விசாரணைக்கு உட்படக்கூடியதாக இருக்கலாம்.
இது தொடர்பான முக்கிய சட்டங்களில்:
* Prevention of Money Laundering Act No. 5 of 2006
* Financial Transactions Reporting Act No. 6 of 2006
* Convention on the Suppression of Terrorist Financing Act No. 25 of 2005
ஆகியவை அடங்குகின்றன.
8. மோசடி தொடர்பாக சந்தேகம் ஏற்பட்டால்
ஒரு நிறுவனம்:
* போலியான உரிமத்தை வழங்கினால்;
* போலியான CBSL/SEC அங்கீகாரத்தைக் கூறினால்;
* போலியான ஆவணங்களைப் பயன்படுத்தினால்;
* தவறான வருமான வாக்குறுதிகளை வழங்கினால்;
* பணத்தைப் பெற்றுக்கொண்டு பின்னர் தொடர்பைத் துண்டித்தால்;
* பணத்தைத் திருப்பிச் செலுத்த மறுத்தால்;
* தனிப்பட்ட வங்கிக் கணக்குகளுக்கு பணம் அனுப்புமாறு கட்டாயப்படுத்தினால்;
* மேலும் நபர்களை இணைப்பதற்காக Commission வழங்கினால்;
சம்பவத்தின் தன்மைக்கு ஏற்ப இலங்கை பொலிஸ்/CID, CBSL, SEC அல்லது தொடர்புடைய ஒழுங்குமுறை அதிகாரிகளிடம் முறைப்பாடு செய்வதை பரிசீலிக்கவும்.
9. பொலிஸ் / CID முறைப்பாடு
மோசடி, போலி ஆவணங்கள், போலி உரிமங்கள், நிதி மோசடி அல்லது இணையவழி நிதி மோசடி தொடர்பாக நியாயமான சந்தேகம் இருந்தால் இலங்கை பொலிஸில் முறைப்பாடு செய்யலாம்.
முறைப்பாட்டில்:
* சம்பவம் நடைபெற்ற திகதி;
* பணத் தொகை;
* நபர்/நிறுவனத்தின் பெயர்;
* வங்கிக் கணக்கு விபரங்கள்;
* தொலைபேசி இலக்கங்கள்;
* ஒப்பந்தங்கள்;
* பிற ஆதாரங்கள்
ஆகியவற்றை தெளிவாக குறிப்பிடவும்.
Online complaint வசதியைப் பயன்படுத்தினால், முறைப்பாட்டு Reference Number-ஐ பாதுகாப்பாக வைத்திருக்கவும்.
⸻
10. CBSL-க்கு முறைப்பாடு
பின்வரும் விடயங்கள் தொடர்பாக CBSL-க்கு தகவல் அல்லது முறைப்பாடு வழங்குவதைப் பரிசீலிக்கலாம்:
* அனுமதியின்றி வைப்புகளைப் பெறுதல்;
* அனுமதியற்ற நிதி வணிகம்;
* “CBSL Approved” என தவறாகக் கூறுதல்;
* சரிபார்க்க முடியாத உரிமம்;
* அனுமதியற்ற Deposit-Taking Scheme.
CBSL Hotline – 1935
11. SEC-க்கு முறைப்பாடு
விடயம் Securities அல்லது Capital-Market நடவடிக்கைகளுடன் தொடர்புடையதாக இருந்தால் SEC-க்கு முறைப்பாடு செய்யலாம்.
குறிப்பாக:
* Shares
* Securities
* Public Offers
* Unit Trusts
* Stockbrokers
* Stock Dealers
* Capital-market intermediaries
போன்ற நடவடிக்கைகளின் ஒழுங்குமுறை நிலையைச் சரிபார்க்கவும்.
12. ஆதாரங்களைப் பாதுகாத்துக் கொள்ளுங்கள்
தொடர்புடைய ஆதாரங்களை நீக்கவோ மாற்றவோ வேண்டாம்.
பணம் செலுத்திய ஆதாரங்கள்
* Bank slips
* Bank statements
* Online transfer confirmations
* Receipts
ஒப்பந்தங்கள்
* Investment Agreements
* Deposit Agreements
* Loan Agreements
* Terms & Conditions
விளம்பரங்கள்
* Facebook Posts
* WhatsApp Messages
* Website Screenshots
* TikTok/YouTube Links
* Posters
* Brochures
தொடர்பாடல்
* Emails
* SMS
* WhatsApp Chats
* Telephone Numbers
* சட்டபூர்வமாகப் பெறப்பட்ட பிற ஆதாரங்கள்
⸻
13. “பணத்தைத் திரும்பப் பெற மேலும் பணம் செலுத்த வேண்டும்” என்று கூறினால்
பணத்தைத் திருப்பித் தருவதற்காக:
“Tax செலுத்த வேண்டும்.”
“Release Fee செலுத்த வேண்டும்.”
“Processing Fee செலுத்த வேண்டும்.”
“Account Unlock Fee செலுத்த வேண்டும்.”
“CBSL Clearance Fee செலுத்த வேண்டும்.”
என்று கூறி மேலும் பணம் கோரப்பட்டால், தொடர்புடைய அதிகாரப்பூர்வ நிறுவனத்திடம் சுயமாக உறுதிப்படுத்தாமல் மேலும் பணம் செலுத்த வேண்டாம்.
14. SLDIS தொடர்பான முக்கிய விடயம்
அங்கீகரிக்கப்பட்ட நிறுவனத்தில் உள்ள தகுதியான Deposit மற்றும் சாதாரண Investment ஆகியவை ஒரே விடயம் அல்ல.
Sri Lanka Deposit Insurance Scheme (SLDIS) தகுதியான வைப்புகளுக்கு அதன் பொருந்தக்கூடிய விதிமுறைகள் மற்றும் வரம்புகளுக்கு உட்பட்டு பாதுகாப்பை வழங்குகிறது.
அது அனைத்து முதலீடுகள், Shares, Securities அல்லது தனியார் Investment Schemes அனைத்திற்கும் உத்தரவாதம் வழங்குகிறது என்று பொருளல்ல.
எனவே, “SLDIS பாதுகாப்பு உள்ளது” என்ற கூற்றை மட்டும் அடிப்படையாகக் கொண்டு முதலீட்டு முடிவெடுக்க வேண்டாம்.
📢 HRPO-வின் பொதுமக்களுக்கான செய்தி
“இலாபத்தைப் பின்னர் பார்ப்போம் – சட்டப் பாதுகாப்பை முதலில் பார்ப்போம்.”
உங்கள் வாழ்நாள் சேமிப்புகள், ஓய்வூதியப் பணம், பிள்ளைகளின் கல்விக்கான பணம் அல்லது வணிகப் பணத்தை எந்தவொரு நிறுவனத்திற்கும் வழங்குவதற்கு முன்:
ஒழுங்குமுறை அதிகாரியை அடையாளம் காணுங்கள்.
உரிமத்தைச் சரிபாருங்கள்.
ஒப்பந்தத்தைப் படியுங்கள்.
அபாயங்களைப் புரிந்துகொள்ளுங்கள்.
ஆதாரங்களைப் பாதுகாத்துக் கொள்ளுங்கள்.
சந்தேகம் இருந்தால் பணத்தை வழங்க வேண்டாம்.
நினைவில் கொள்ளுங்கள்:
“Pvt Ltd” நிறுவனமாக இருப்பது மட்டுமே பொதுமக்களிடமிருந்து வைப்புகளைப் பெறுவதற்கான அதிகாரம் பெற்றுள்ளது என்று அர்த்தமல்ல.
“CBSL Approved” என்ற எந்தக் கூற்றையும் அதிகாரப்பூர்வ ஆதாரங்கள் மூலம் சரிபார்க்கவும்.
“Guaranteed Profit” என்ற வாக்குறுதியை மட்டும் நம்பி முதலீடு செய்ய வேண்டாம்.
உங்கள் பணம் – உங்கள் பொறுப்பு – உங்கள் சட்ட உரிமை.
⸻
மனித உரிமைகள் பாதுகாப்பு அமைப்பு (HRPO), இலங்கை
பொதுமக்களின் பொருளாதார உரிமைகள், நுகர்வோர் உரிமைகள் மற்றும் சட்டப் பாதுகாப்பு தொடர்பான விழிப்புணர்வை ஏற்படுத்தும் நோக்கில் இந்தப் பொதுமக்கள் விழிப்புணர்வு அறிவிப்பு வெளியிடப்படுகிறது.
டாக்டர் M. M. Shafaan
நிறைவேற்றுப் பணிப்பாளர்
மனித உரிமைகள் பாதுகாப்பு அமைப்பு (HRPO), இலங்கை
humanrightspo.org
www.asianews.lk
www.bbcmirror.lk
www.asianewsplusone.com
www.sfmnewslk.com
www.Lankawebnews.lk
www.ceylonwebrepoter.com
www.ceylonwebnews.com
www.ceylonnewsmedia.com
chat.whatsapp.com/Knsroge4upyJzBjJLvNMQS?mode=gi_c
https://youtube.com/@bbcmirror?si=gUipLaxS2au3wav-
www.instagram.com/bbcmirror_media_?igsh=MW5seTc0eW1yYmVsNw%3D%3D&utm_source=qr